A car carrier's certificate of insurance should clearly show the carrier's exact legal name and USDOT or MC number, the insurance company, current policy dates, the cargo coverage limit and deductible, and auto liability coverage. Those details should match the carrier's record on the FMCSA website, and the cargo limit should be high enough for the value of your car. If any of those items are missing, expired or don't match, ask questions before your car is loaded.
Key takeaways
- The key document is the certificate of insurance (COI), a one-page summary of the carrier's policies.
- Cargo insurance pays for damage to your car; auto liability covers damage the truck causes to others.
- The name, USDOT or MC number and policy dates on the COI should match the carrier's FMCSA record.
- Check the cargo limit per vehicle and per load, the deductible, and any exclusions.
- High-value cars may need a carrier with higher cargo limits, often found with enclosed transport.
The documents you may see
When you ask about insurance, you will usually be shown a certificate of insurance, often called a COI. It is a short summary form issued by the carrier's insurance agent. It does not list every term of the policy, but it shows the main facts you need.
You may also hear about a few related items:
- FMCSA operating authority: the federal registration that lets an interstate for-hire carrier haul cars across state lines. It is tied to a USDOT number and usually an MC number.
- Liability filing: carriers file proof of their liability insurance with FMCSA. You can see whether it is on file using the agency's public lookup tools.
- Broker bond: brokers must keep a $75,000 surety bond or trust on file with FMCSA. This is not cargo insurance for your car, but it is part of a broker's legal setup.
- Your own auto policy: your personal car insurance may or may not cover the car while it is on a carrier. Call your insurer and ask.
Line by line: what a carrier COI should show
Here is what to look for on the certificate and why it matters.
| Field on the COI | What it should show | Red flag |
|---|---|---|
| Insured (named carrier) | The carrier's exact legal business name and address | Name differs from the company on your dispatch or BOL |
| USDOT / MC number | Often listed in the description area | Missing or doesn't match FMCSA |
| Insurer | The insurance company that issued each policy | No company listed, or only an agent |
| Policy numbers | A number for each coverage type | Blank policy numbers |
| Effective and expiration dates | Dates that cover your full shipment | Expired, or expires mid-trip |
| Auto liability limit | Typically $750,000 to $1,000,000 or more | Below the federal minimum |
| Motor truck cargo limit | A per-vehicle and/or per-load limit high enough for your car | Limit lower than your car's value |
| Cargo deductible | The amount the carrier pays before insurance | Very high deductible with no explanation |
| Description of operations | Notes such as "auto hauler" or covered vehicle types | Coverage that excludes the kind of car you are shipping |
| Certificate holder | Often the broker or shipper requesting it | Not a problem by itself; just shows who asked |
Cargo insurance vs. auto liability
People often mix these up, but they cover different things.
Motor truck cargo insurance
This is the coverage that matters most to you. It pays for physical damage to the cars the truck is hauling, subject to the policy's terms, limits and deductible. For most car carriers, FMCSA does not set a federal minimum for cargo coverage, so limits vary from carrier to carrier. That is why you should check the amount.
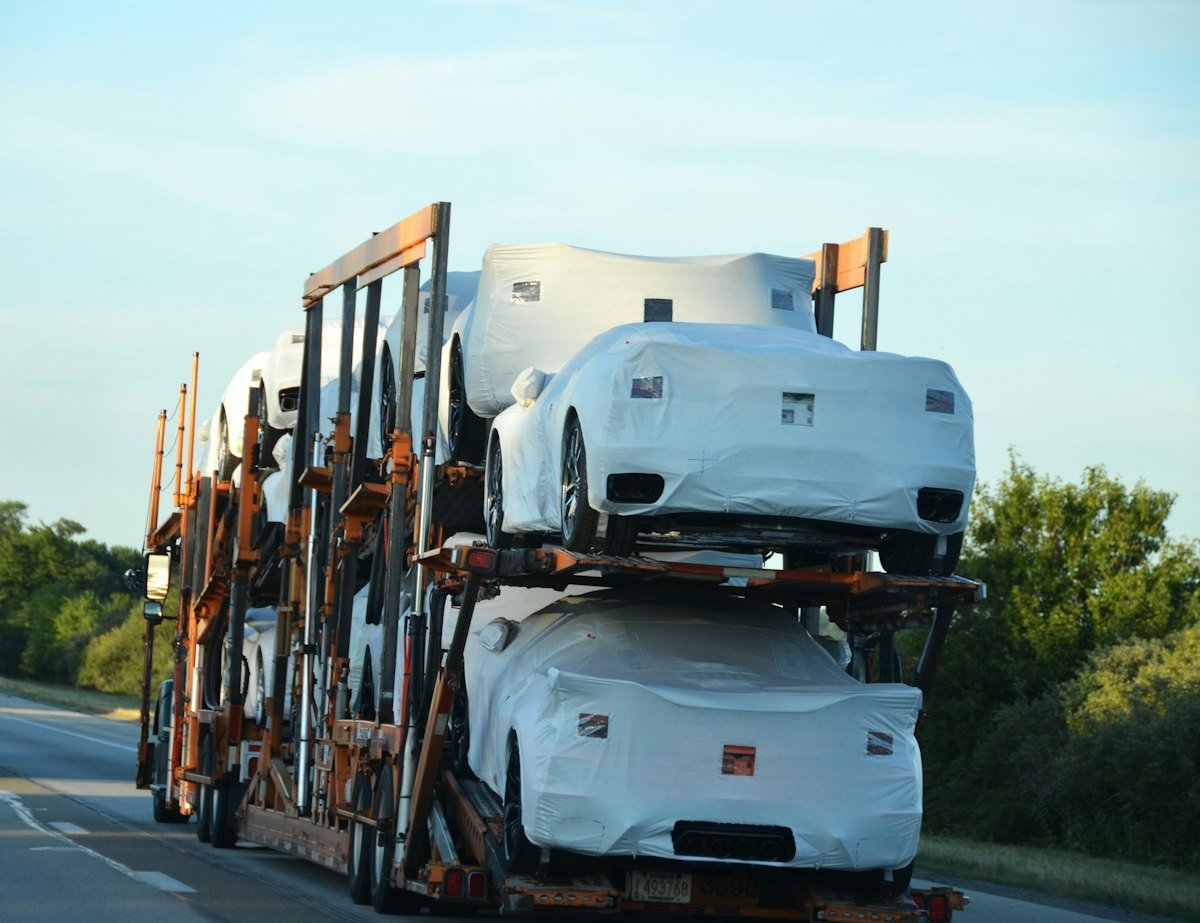
Open carriers commonly carry cargo limits in the low-to-mid six figures per load, while enclosed carriers that move exotics and classics often carry much higher limits. Divide the per-load limit by the number of cars on the truck to get a rough sense of how much is available per car, unless the policy states a per-vehicle limit.
Auto liability insurance
This covers injuries and property damage the truck causes to other people, for example in a crash. Federal rules typically require at least $750,000 for interstate for-hire carriers hauling general freight in heavy trucks, and many carriers carry $1,000,000. It does not pay for damage to your car on the trailer.
How to verify a carrier's insurance
A COI is just a piece of paper. Take a few minutes to confirm it is real and current.
- Look up the carrier on FMCSA. Search the USDOT or MC number on the FMCSA SAFER or registration lookup and confirm the legal name, address and that the authority is active.
- Check the insurance filing. The FMCSA records show whether liability insurance is on file and which company filed it.
- Match names exactly. The carrier on the COI should be the same company named on your dispatch confirmation and the bill of lading.
- Check the dates. Make sure the policies cover the whole time your car is in transit.
- Confirm with the agent if needed. The COI lists the producer (the insurance agent). For high-value shipments, it is reasonable to have the broker confirm the policy is active with that agent.
- Ask about exclusions. Some policies exclude certain vehicle types, values, or damage caused by weather or road debris.
A good broker does this checking for you before assigning a carrier. CTS arranges shipments through Niki Auto Transport (USDOT 4535689, MC 1799148) and works only with licensed and insured carriers from a network of more than 100,000.
How much cargo coverage does your car need?
Match the coverage to the value of what you are shipping.
| Vehicle type | What to look for |
|---|---|
| Everyday sedan, SUV or pickup | Standard open-carrier cargo coverage is usually enough |
| New or high-trim vehicle | Confirm per-vehicle coverage clearly exceeds the car's value |
| Classic or collector car | Higher limits; check agreed-value questions with your own insurer |
| Exotic or supercar | Enclosed carrier with high cargo limits; coverage up to $2M can be arranged |
| Multiple cars on one load | Check the per-load limit against the total value |
For expensive vehicles, luxury and exotic car shipping and enclosed car shipping usually come with carriers that hold larger policies.
What carrier insurance usually doesn't cover
Every policy is different, but these are common limits to ask about:
- Personal items left in the car. Cargo policies generally cover the vehicle, not belongings inside it.
- Pre-existing damage. That is why your pickup condition report matters.
- Mechanical problems that are not caused by the transport.
- Damage not noted at delivery, which is much harder to claim.
- Certain weather events or acts of nature, depending on the policy.
- Loose or aftermarket parts that were not secured or removed.
Your own auto policy may fill some gaps. Call your insurer before shipping and ask whether your comprehensive coverage applies while the car is on a carrier.
If damage happens: how insurance comes into play
- Note the damage on the bill of lading at delivery, before signing.
- Take photos and video before the truck leaves.
- Report it to your broker or carrier the same day, in writing.
- Get a written repair estimate.
- The carrier decides whether to pay directly or file with its cargo insurer. The deductible usually is the carrier's responsibility, not yours.
For more on this, read our guide to preparing your car and our car shipping FAQs.
Real-world examples of coverage questions
These short examples show how the details on a COI can matter. They are general illustrations, not legal advice, and every policy is different.
A new SUV on a full open carrier
An open carrier is hauling nine cars, and its cargo policy shows a per-load limit. If several of those cars are new SUVs, the total value of the load could be close to or above the limit. That doesn't mean your car is unprotected, but it is a good reason to ask whether the policy also has a per-vehicle limit and how a large loss would be handled.
A classic car worth more than book value
A restored classic may be worth far more than a standard pricing guide suggests. Carrier cargo coverage usually pays actual damage within the policy's terms, so owners of collector cars often also carry an agreed-value policy from a classic car insurer. Ask that insurer whether coverage continues while the car is on a carrier.
A COI that expires next week
If the policy expiration date falls in the middle of your car's trip, ask the broker to confirm the policy has been renewed. Many policies renew without a gap, but you want that confirmed before pickup.
A name mismatch
The COI lists one company, but the truck that arrives shows a different name on the door. Sometimes this has an innocent reason, such as a parent company or a recently updated name, but you should still stop and ask the broker to confirm before your car is loaded. Never let the car go on a truck you can't match to your paperwork.
Keeping your own records
Insurance works best when your paperwork is in order. Keep these together, in a folder or a single cloud album, until your car is delivered and any claim is closed:
- Your written quote and booking confirmation.
- The carrier's name, USDOT and MC numbers.
- A copy of the carrier's certificate of insurance.
- Your dated pickup photos and video.
- The signed bill of lading from pickup and delivery.
- Any messages about delays or damage.
Our guide to how car shipping works shows where each of these documents appears in the process.
Questions to ask before you book
- Can you send the carrier's certificate of insurance before pickup?
- What is the cargo limit per vehicle, and per load?
- What is the deductible, and who pays it if there is a claim?
- Are there exclusions for my type of vehicle?
- Is the carrier's FMCSA authority active?
- Is higher coverage available for my car if needed?
Asking these questions is normal. A reputable company will answer clearly and won't pressure you to skip them.
Frequently asked questions
Is my car insured while it's being shipped?
The carrier's cargo insurance generally covers damage caused during transport, within the policy's limits and terms. Your own policy may also apply, so check with your insurer.
Can I see the insurance certificate before pickup?
Yes. It's reasonable to ask for the carrier's COI once a carrier is assigned.
What if the COI name doesn't match the truck that shows up?
Stop and ask your broker before loading. The carrier on the paperwork should be the carrier moving your car.
Do brokers carry cargo insurance?
Some do, but brokers usually rely on the assigned carrier's cargo policy. Brokers must hold a $75,000 bond or trust with FMCSA, which is a separate requirement.
Should I buy extra insurance for an expensive car?
For high-value cars, ask about higher coverage options and check with your own insurer. CTS can arrange coverage up to $2M on qualifying shipments.
Want a carrier whose paperwork checks out before your car moves an inch? Get a free quote and ask us for the carrier's certificate once you're booked.
Updated November 4, 2026